Ghana Auditor-General Reports GH¢18bn Recovered, but Audit Records Reveal Accountability Gap
Ghana's Auditor-General reports over GH¢18bn recovered and GH¢11.7bn in prevented payments, but a 41.8% implementation rate raises questions about audit follow-through.


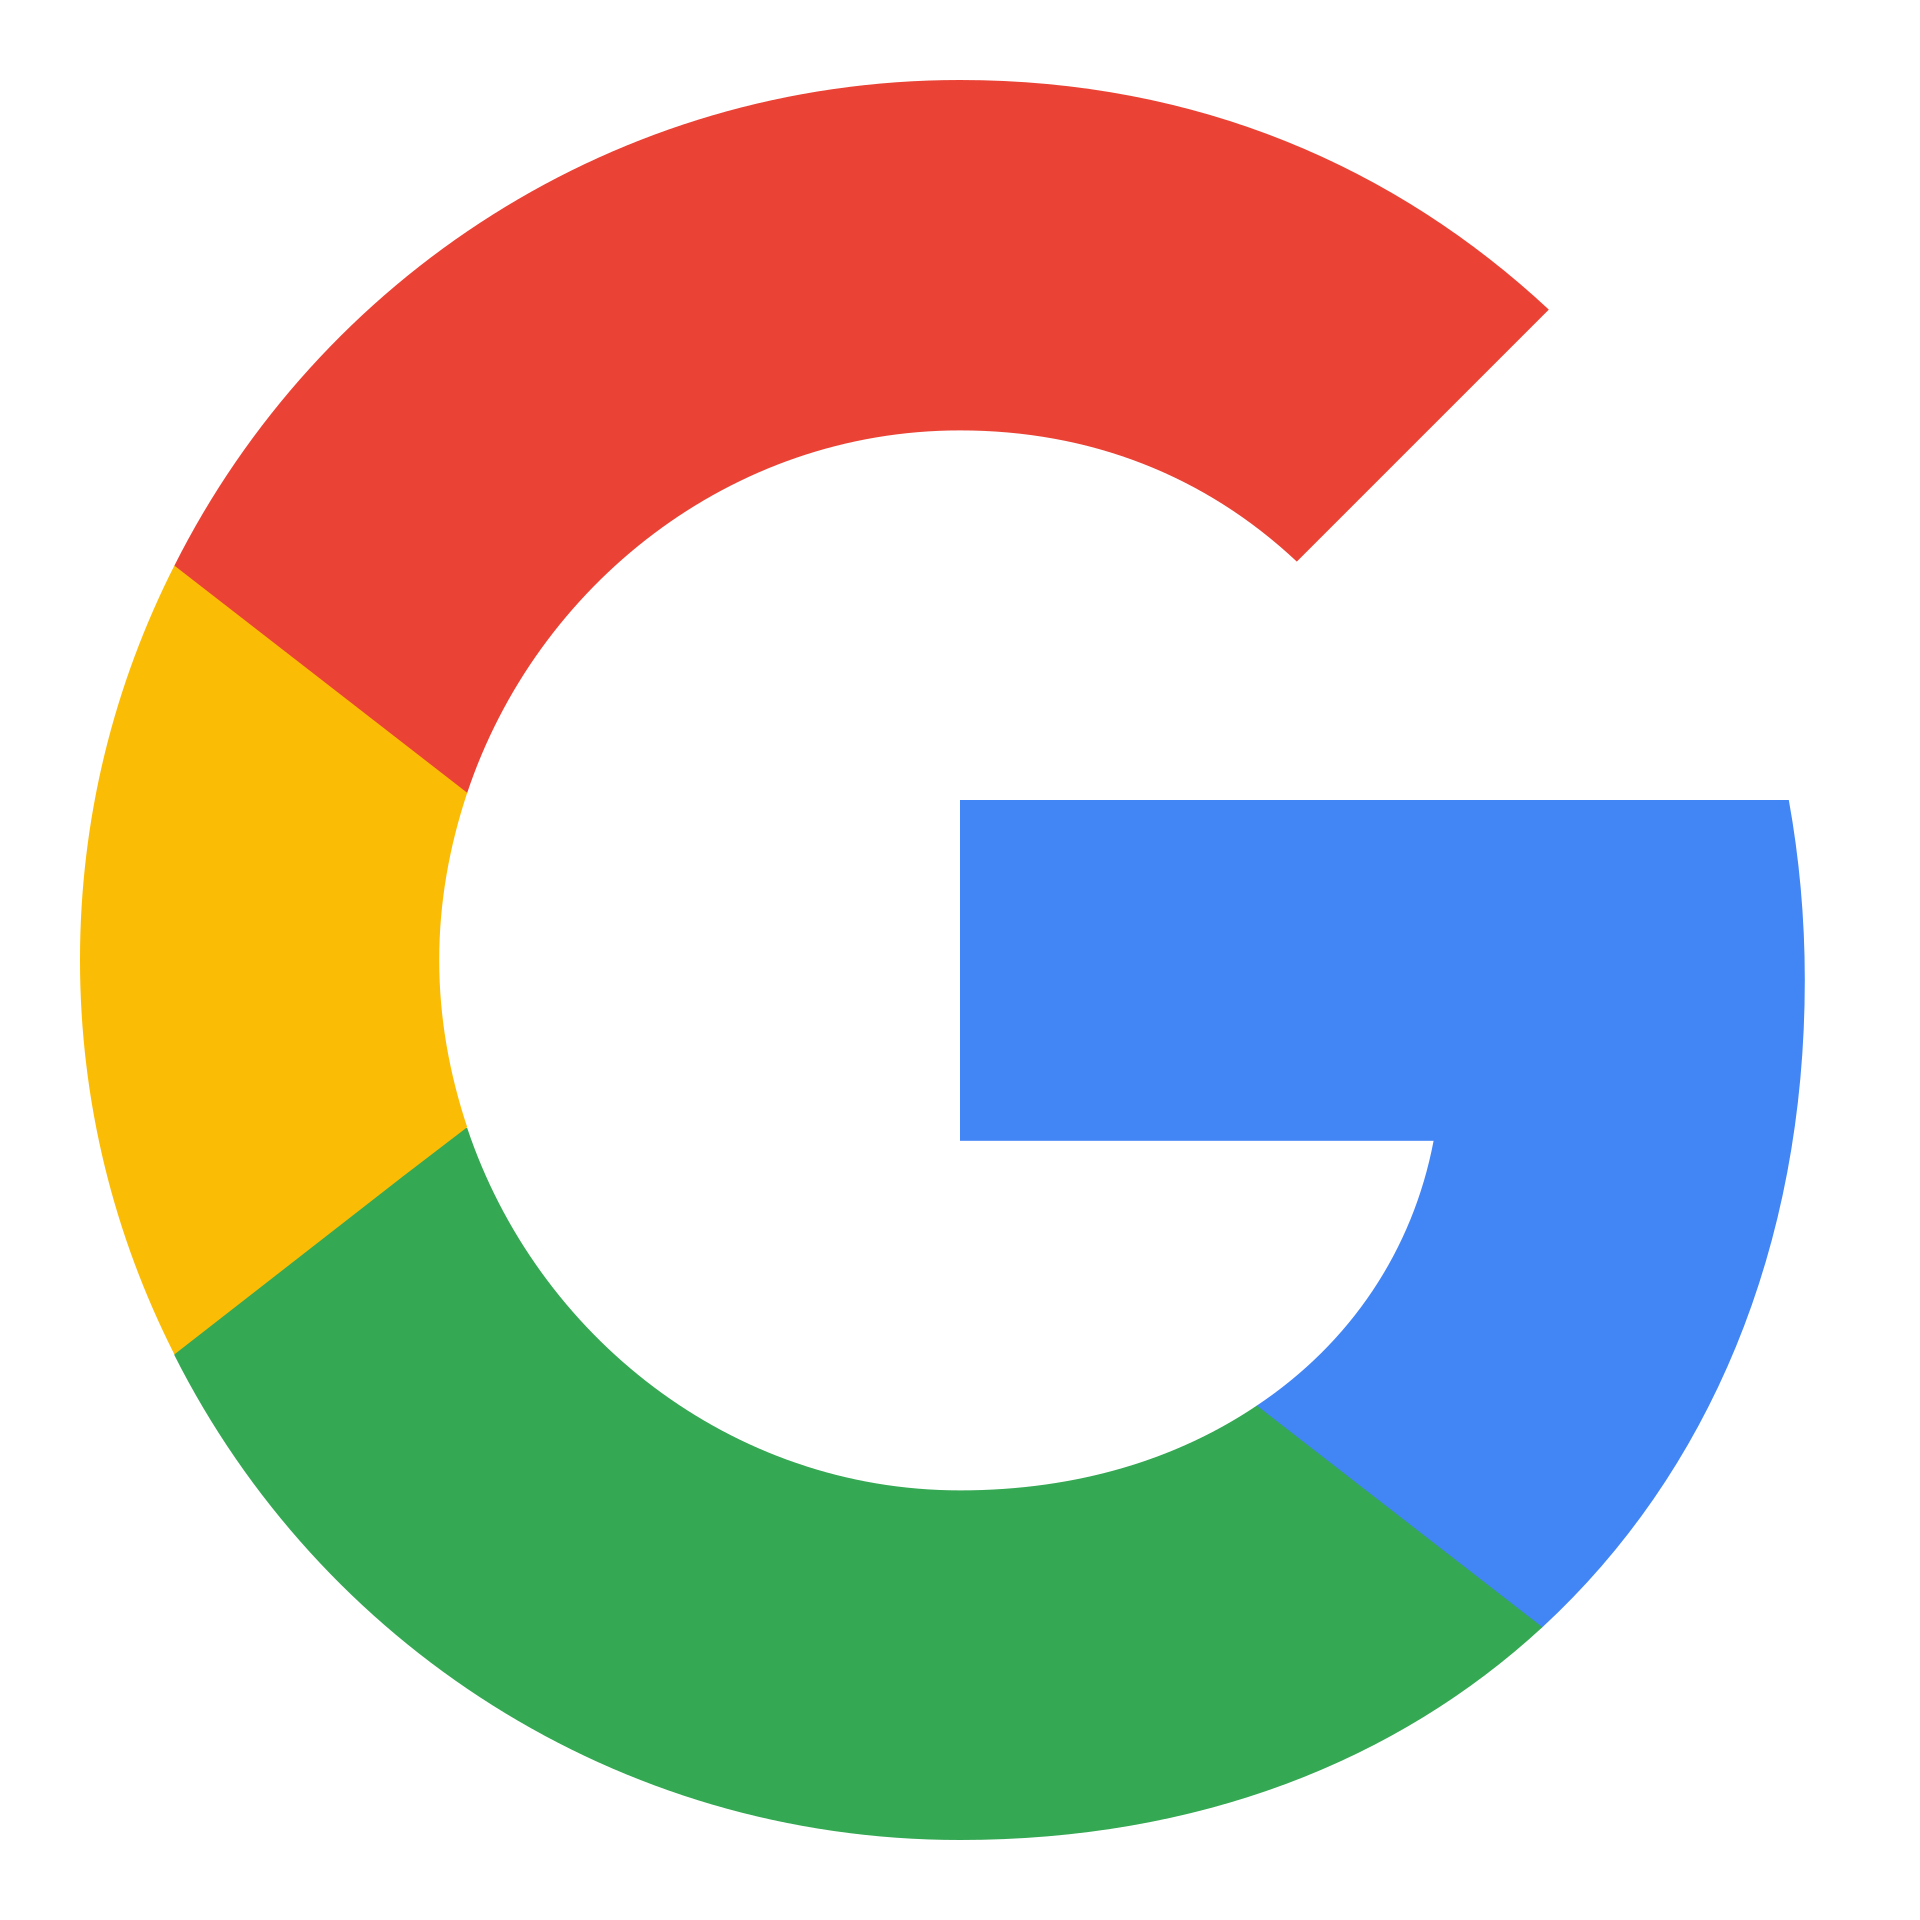
Ghana’s Auditor-General says more than GH¢18 billion has been recovered through audit recommendations since 2022, yet the reported implementation rate remains 41.8%. Official audit records reveal why recovery, prevented expenditure and implementation must be assessed separately.
ACCRA — Auditor-General Dr Pamela Graham reported more than GH¢18 billion recovered since 2022 and GH¢11.7 billion in wrongful payments prevented during 2025. The claims were made at the African Organisation of Public Accounts Committees conference in Accra. The reported 41.8% implementation rate raises a separate question: how consistently are public institutions acting on audit recommendations?
Ghana Audit Recoveries: What the Numbers Mean
Five different accountability measures, one important question: how much public money has actually been recovered?
Editorial snapshot: 3 November 2026Explore the five financial measures
Historical special audit: recommended versus recovered
Calculated historical balance: GH¢26.27bn. This is not a verified outstanding balance in November 2026.
Historical recoveries by audit-report year
Explore the 2020–2023 report-year breakdown in the special audit.
Year labels refer to the original audit reports, not necessarily the year cash was received.
Reported recommendation implementation
These percentages concern recommendations, not public money. The underlying denominator and treatment of partial implementation require verification.
Why the headline totals cannot simply be added
The GH¢18bn-plus recovery claim, GH¢11.7bn in prevented payments, GH¢12.72bn historical special-audit recoveries and GH¢57.2m in dedicated-account receipts measure different activities, periods or collection channels.
Without a published reconciliation, adding them would risk double counting or mixing money recovered with losses prevented.
What the Auditor-General announced
According to reports, Graham attributed the cumulative GH¢18 billion recovery figure to follow-through on audit recommendations. She separately cited GH¢11.7 billion in payments prevented in 2025. These figures should not be added together and labelled recovered cash: one concerns recoveries over multiple years, while the other concerns payments reportedly stopped before they occurred.
Explainer: five different financial and accountability measures
| Measure | Reported figure | What it describes |
|---|---|---|
| Recoveries announced since 2022 | More than GH¢18bn | Cumulative recovery claim made in November 2026 |
| Wrongful payments prevented in 2025 | GH¢11.7bn | Avoided payments, not money recovered after payment |
| Special audit recoveries through December 2024 | GH¢12.72bn | Recoveries within a specified historical audit scope |
| Dedicated recovery-account collections since 2022 | About GH¢57.2m | Receipts into a particular account, not necessarily all recoveries |
| Recommendations implemented | 41.8% | Follow-through on audit recommendations, not a cash recovery rate |
The figures come from different reporting periods and accounting categories. They should not be treated as interchangeable or assumed to reconcile without a published bridge between them.
What the official special audit found
An Audit Service special report on recoveries from disallowed expenditure for 2020–2023 identified GH¢38.99 billion recommended for recovery and GH¢12.72 billion recorded as recovered by December 2024. The arithmetic recovery proportion is 12.72 divided by 38.99, or approximately 32.6%; the calculated balance is GH¢26.27 billion. That historical balance must not be presented as the amount outstanding in November 2026.
Why is the recovery-account total much smaller?
In September 2026, the Audit Service reported approximately GH¢57.2 million collected through the Auditor-General’s dedicated recovery account since 2022. That is a narrower channel than all possible recoveries arising from audit recommendations, including amounts recovered directly by public institutions. The difference is not proof that the GH¢18 billion claim is wrong; it is a reason to request a reconciliation of cash receipts, debt settlements, accounting adjustments and the institutions credited with recoveries.
What does 41.8% implementation mean?
Graham reported an audit-recommendation implementation rate of 41.8%, compared with figures of 65% for Rwanda, 34% for South Africa and 18% for Morocco. Ghana’s rate is 23.2 percentage points below the cited Rwanda figure, 7.8 points above South Africa and 23.8 points above Morocco. These are comparisons of reported percentages, not independently standardised international rankings: the available conference reporting does not establish identical periods, recommendation types or measurement methods.
The complementary 58.2% represents recommendations not counted as implemented under the reported measure. It is not the percentage of public money unrecovered. Audit recommendations may concern procurement controls, records, administration or governance as well as financial recoveries.
What should be independently verified?
- A year-by-year schedule reconciling the GH¢18 billion cumulative recovery claim to underlying financial statements.
- The extent to which recoveries were cash received, debt settled or accounting adjustments.
- The relationship between the dedicated recovery account and recoveries handled directly by ministries and agencies.
- The denominator, reporting period and definition of full versus partial implementation behind the 41.8% figure.
- Whether the announced Audit Recommendations Tracker is operating and provides complete public records.
Why the distinction matters
Audit success is not captured by a single headline amount. Recovering money after an irregular payment is valuable, but preventing a wrongful payment is different, and implementing controls that prevent recurrence is another outcome altogether. Readers need consistent definitions and auditable supporting records to assess whether the reported gains are durable.
Editorial methodology, 3 November 2026: The GH¢18 billion and GH¢11.7 billion totals are attributed to the Auditor-General’s reported remarks. The special-audit arithmetic is calculated from the stated figures. Different reporting periods, account scopes and definitions have not been independently reconciled. No figure here is presented as a current outstanding balance without supporting evidence.
Related posts:
 Ghana Prisons Service questioned over GH¢277,625 in inmates’ wages used for other expenses
 Bank of Ghana suspends proposed 0.75% mobile money transfer fee
 Three Arrested in Police Raid on Illegal Mining Site Along Ghana Water Pipeline
 Ghana’s GoldBod Generates $1.87 Billion in Foreign Exchange in September
 Ghana records GH¢209.7m in reported cyber losses in nine months as incidents reach 4,938.